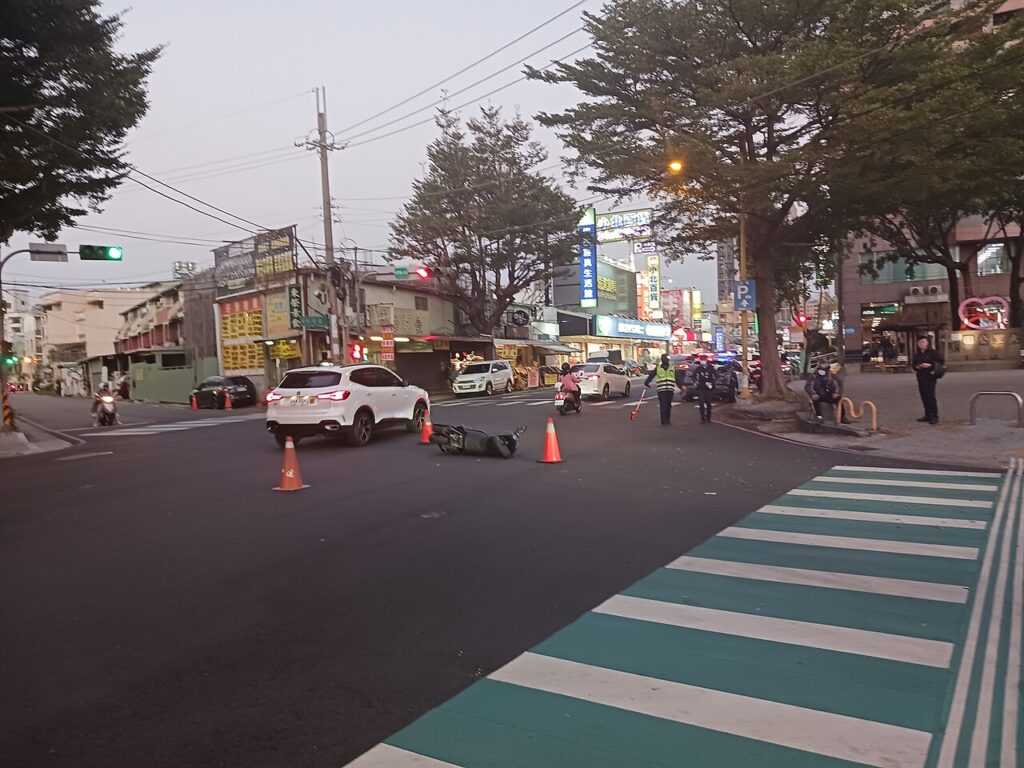
An insurance claim is where the policy you bought meets the process you did not read. Every state writes its own claim rules — deadlines, adjuster response times, total-loss thresholds, and how long you have to sue. This guide maps the claim process state by state for 2026, explains the steps that keep claims moving, and covers the dispute playbook when the first offer is too low.

The claim timeline, in order
Report the accident to your insurer within 24 to 72 hours — some policies require ‘prompt notice’ and delay hurts you. Get a claim number and the adjuster’s contact. The insurer assigns an adjuster who inspects the vehicle (or reviews photos through modern apps), produces an estimate, and issues payment minus your deductible. Rental coverage runs concurrently if you bought it. In injury claims, PIP or med-pay processes separately from the vehicle claim. The whole property process typically runs one to three weeks for repairable cars and three to six weeks for total losses in cooperative claims.
State deadlines and statutes of limitations
| Rule | Typical range | Why it matters |
|---|---|---|
| Notify insurer | 24h–14 days | Late notice is a top denial reason |
| File a claim lawsuit (property) | 2–6 years | Statute of limitations by state |
| PIP medical deadlines | 14 days (FL)–1 year | Missing the treatment window voids PIP |
| Adjuster response | 15–40 days mandated in some states | Unfair-claims-practices acts |
| Total-loss settlement | 30–60 days after offer in regulated states | States enforce prompt-pay laws |
Total loss: the valuation fight
A car is totaled when repair cost approaches its actual cash value — states set the line anywhere from 70 percent (several Southern states) to 100 percent plus Minnesota’s famous ’90 percent of market value’ standard. The insurer’s offer is an estimate, not a command. Request the comparable-vehicles report, check that the comps match your trim, mileage and region, and push back with your own listings. Diminished-value claims — the resale hit even after perfect repairs — are recognized in most states against the at-fault driver’s insurer, and are almost never offered voluntarily.
Where states differ most
- No-fault states route medical through PIP with strict treatment windows — Florida’s 14-day rule voids claims silently
- Prior notification states require an adjuster inspection before repair; photo-estimate states do not
- Some states mandate that insurers pay sales tax on total-loss settlements; others leave it to policy terms
- Unfair claims practices acts vary: a handful of states publish hard response deadlines with real penalties; the rest rely on complaint-driven enforcement
- Glass coverage: zero-deductible windshield replacement is a state-legislated perk in Florida, Kentucky, South Carolina, Arizona and Massachusetts
The dispute playbook
When an offer is too low: request the valuation report in writing and every comparable used. Rebut with your own comps within the carrier’s process. Escalate to the claims manager. Then invoke your state’s insurance department — complaints are free, tracked, and materially change insurer behavior because departments audit complaint ratios. Appraisal clauses exist in most policies: you hire an appraiser, the insurer hires one, the two select an umpire; each side pays its own. Finally, a public adjuster (typically 5 to 10 percent of the settlement) pays for itself on large or contested property claims.
The mistakes that sink valid claims
- Admitting fault at the scene — fault is determined by evidence, not apologies
- Skipping the police report in injury crashes — insurers treat unreported crashes skeptically
- Delaying medical treatment; gaps become pre-existing condition arguments
- Accepting the first offer verbally without getting it in writing
- Signing broad medical releases that let the insurer trawl your entire history
- Letting repairs start before reading the estimate’s depreciation and OEM-parts lines
Frequently asked questions
The first 48 hours after the crash
The claim’s outcome is shaped before the tow truck arrives. Photograph everything: vehicle positions before moving, all damage, license plates, the other driver’s insurance card, the surrounding intersection, skid marks. Get the police report number even when the police decline to come — many states allow accident reports filed online after the fact, and insurers weight police-documented facts heavily. Exchange information but do not negotiate fault at the scene; fault is an evidence question, and roadside apologies become exhibit A.
The recorded statement: your only mandatory obligation, handled carefully
Your own insurer can reasonably ask for a recorded statement; the other driver’s insurer cannot compel one from you, and their adjusters are professionals at turning casual answers into comparative-fault arguments. The rule: cooperate fully with your own carrier, decline politely and in writing when the third-party adjuster asks for a recorded statement before you have reviewed the police report. This is not evasion — it is the standard advice every state’s own insurance-prepared consumer guides echo.
Rental car and loss-of-use coverage, decoded
Rental reimbursement is the daily-amount-per-day-limit product you bought (or didn’t) — $30/day for 30 days is typical. Two things surprise people: the coverage pays only for days the shop is actually repairing (or the total-loss window the insurer reasonably needs), and ‘loss of use’ claimed from the other driver’s insurer can exceed your own rental limits when their driver is clearly at fault. If the at-fault insurer stalls, your rental coverage fronts the money and your carrier subrogates — that is exactly what subrogation departments exist to do.
The subrogation process and your deductible
When their driver was at fault, your insurer pays you fast (minus your deductible), then chases the other insurer for reimbursement — that chase is subrogation. When it succeeds, your deductible comes back to you, often six to twelve weeks later, automatically. It fails when fault is disputed, which is the quiet argument for buying the police report, keeping photos organized, and answering your adjuster’s calls. Deductible recovery is routine but not guaranteed; persistence and clean evidence decide it.
State-specific consumer protections worth knowing
| Protection | Where it applies | What it does |
|---|---|---|
| Prompt-pay statutes | Most states | Deadlines for insurer payment after proof of loss |
| Zero-deductible glass | FL, KY, SC, AZ, MA | Free windshield replacement on comprehensive policies |
| Appraisal clause | Standard in most policies | Independent valuation fight for total-loss offers |
| External medical review | PIP states | Independent doctor reviews disputed treatment |
| Complaint-index publishing | All states via NAIC | Insurer behavior transparency by market share |
When to hire a public adjuster or attorney
Public adjusters (property damage, 5–10 percent of settlement) earn their fee on large or contested claims — fire, flood, disputed total losses. Attorneys on injury claims work on contingency (typically 33 percent), which pencils out when injuries are permanent or liability is contested, and does not on soft-tissue claims that settle for policy limits anyway. The decision rule: professional help when the delta they can move exceeds their percentage — roughly, claims above $15,000, disputed liability, or any permanent injury.
The repair-shop question: insurer network versus your choice
In every state you have the legal right to choose your repair shop; the insurer may suggest a direct-repair-program shop but cannot require it. DRP shops streamline billing and often produce fast, good work — the insurer monitors them, which cuts both ways. Independent shops may advocate harder for OEM parts and proper procedures because their customer is you, not the insurer. Practical rule: for cosmetic damage, DRP speed wins; for structural, sensor-heavy repairs on newer cars, an independent shop with OEM documentation often produces the better file.
Diminished value and total loss, state by state
Georgia is the famous diminished-value claimant’s state after a landmark Supreme Court decision; most states recognize the concept against at-fault insurers with varying enthusiasm; a handful restrict it. Total-loss thresholds range from 70 percent of value to 100 percent — the same crashed car totals in one state and repairs in another. Both facts matter most to owners of newer vehicles: check your state’s threshold before assuming a repair is realistic, and check your state’s DV precedent before accepting a total-loss offer that ignores your car’s post-repair value loss.
Frequently asked questions
Should I file a claim for a small accident?
If damage is under your deductible plus a small margin and no one was hurt, paying out of pocket protects your claims-free discount — worth 20 to 30 percent of the premium.
Can my insurer raise my rate for a not-at-fault claim?
In some states, yes — not-at-fault claims can raise rates slightly, though less than at-fault ones.
How long does an insurer have to pay a total loss?
Prompt-pay laws in most states require settlement within 30 to 60 days of a completed proof of loss.
What if the other driver is uninsured?
Your uninsured motorist coverage (if you bought it) and your collision coverage respond; beyond that, your claim is against their personal assets.
{“@context”:”https://schema.org”,”@type”:”FAQPage”,”mainEntity”:[{“@type”: “Question”, “name”: “Should I file a claim for a small accident?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “If damage is under your deductible plus a small margin and no one was hurt, paying out of pocket protects your claims-free discount u2014 worth 20 to 30 percent of the premium.”}},{“@type”: “Question”, “name”: “Can my insurer raise my rate for a not-at-fault claim?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “In some states, yes u2014 not-at-fault claims can raise rates slightly, though less than at-fault ones.”}},{“@type”: “Question”, “name”: “How long does an insurer have to pay a total loss?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Prompt-pay laws in most states require settlement within 30 to 60 days of a completed proof of loss.”}},{“@type”: “Question”, “name”: “What if the other driver is uninsured?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Your uninsured motorist coverage (if you bought it) and your collision coverage respond; beyond that, your claim is against their personal assets.”}}]}


 The Kitchen - Spot the differences
 Sokoballs
 Strykon
 Football Masters
 Drive Crazy
 Stickman Warriors
 Golf Orbit
 Morphit
Leave a Reply